

In 1987, Hong Kong’s markets were doing excellently well.
GDP growth was in double digits.
And therefore stock markets were buzzing.
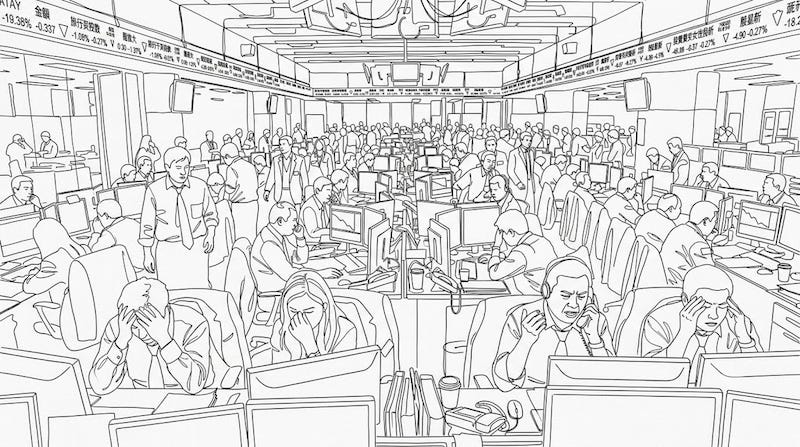
On 19 Oct 1987, the infamous Black Monday happened. The Hong Kong markets fell by 11%. The US markets had already been sliding for a week before that.
Then, the US stock markets fell over 20% in a single day.
What followed was an absurd wave that hit both sides of the world.
The chairman of the exchange in Hong Kong decided to “prevent” this spread of panic. He ordered the markets to be shut down for 4 days.
His logic was that if the markets were shut, panic would not spread (and share prices would not fall).
Later, when the markets opened, the investors were even more scared, because the markets had been forced to shut down — something they just did not expect.
A massive sale took place.
The markets fell a further 33%, making matters much worse.
But why?
Why did a sudden crash in the US also cause a crash in the Hong Kong markets?
And why did shutting the markets down only worsen the situation?
The answer — it’s all connected. Investors from across the globe invest in different stock markets.
And their behavior can lift, or crash different markets.
In that light, it makes sense to understand the main factors that affect their behavior.
Interest Rates Reduction
This is one of the biggest factors affecting how global investors invest (or withdraw).
In India, these global investors are called FIIs or Foreign Institutional Investors.
The core mechanism behind this is bond rates. Specifically, US bond rates.
From time to time, the US Fed adjusts its target interest rate range. This is done with the aim of either controlling inflation (by increasing interest rates) or spurring economic growth (by decreasing interest rates).
The mechanics behind this are bit lengthy and is a topic for another edition of this digest.
But those interest rate targets affect most major bond rates.
The US government bonds are considered the safest investment in the world.
So investors love investing in them.
But, their returns are pretty low compared to other options.
Most investors own a basket of different types of assets. Some money is in US government bonds, some in US stocks, some in stocks of other countries, etc.
And these investors have a desired or target return in their mind for their investments.
Whenever bonds’ interests are reduced, especially the US government bonds’ interest, investors start moving money around.
So, they take out money from US bonds and move it to higher risk but higher return investments.
In short, the reduced interest rates mean they must take on more risk to reach their target returns.
So now, more money flows into riskier assets.
Some money moves from US government bonds to corporate bonds, US companies shares, developing countries’ stocks, startups, etc.
If interest rates are reduced further, even more money will get moved from US government bonds into riskier investments.
Obviously each of these investment-categories carries with it a different level of risk, and is expected to yield different kinds of returns.
US companies’ shares are usually expected to give lower returns than emerging markets’ stocks.
Startup investments are expected to give some of the highest returns while also being extremely risky.
After the dot-com bubble in 2000, the US Fed reduced interest rates to around 1%. Lots of money flowed into emerging markets including India.
We saw this repeat after the US Fed reduced interest rates post the recession in 2008.
And yet again, in 2020, when they reduced interest rates as a response to the slowdown caused by the pandemic.
Interest Rates Increased
The flip side of this is when interest rates are hiked.
The opposite happens.
Why should investors take more risk when they can earn the same returns while taking on less risk?
So when interest rates are increased, some money leaves these riskier categories and moves into less risky categories, like US government bonds, US corporate bonds, etc.
At the extreme end, it means less money is available for startup investments.
Money also flows out of emerging markets’ stocks, and other riskier investments.
After cutting interest rates post 2000, the US Fed started increasing interest rates in 2004. As the rates kept on being increased, money started flowing in the other direction. 2006 saw Indian markets dip by 20-30% in about a month.
The same happened in 2013, when the US Fed hinted at reducing quantitative easing (QE).
Similar patterns could be observed a few times after that as well like in 2018 and 2022-23.
Sentiments
If it were just interest rates, things would have been simpler. But obviously it is not.
Interest rates are one of the biggest factors for sure, but another factor that plays a big role is the perception of certain investments.
Investors don’t just blindly move money based on interest rates.
If a country’s markets seem more promising, more money will be moved there. If US companies’ shares show more promise, more money will move there.
If everything looks gloomy and negative, money will start moving into US government bonds — even without any interest rate change.
This is why any news of conflict can cause money to move from riskier assets to less risky assets.
That is, money starts moving away from emerging markets like India towards the US stocks and bonds markets.
We saw the same during the start of the pandemic in 2020. Everybody was selling everywhere and moving money into US bonds or gold.
One really good example of this is Brexit in 2016.
Britain voted to leave the European Union. Nothing else had changed: no interest rate changes, no regulatory changes, etc.
But investors sold UK assets and moved their money into US bonds, Japanese Yen, and other markets.
The first wave of panic that hit the Hong Kong stock market was mostly because of sentiments.
Comparison
Money can also move simply because new opportunities show up.
Investors love investing in undervalued assets. So, let’s say the stock markets of one country are fairly valued but for some reason, other countries’ stock markets suddenly seem very undervalued.
This is enough to trigger a sell-off even though nothing changed in the country or its companies.
Not just countries, money can move between asset classes too.
The sudden technological boom driven by AI has caused a lot of money to move into tech sector investments (AI related stocks and bonds).
This money would have come from somewhere. Investors would have sold bonds, others stocks, commodities like gold, etc to invest in tech stocks and bonds.
One recent example of this is from the 2nd part of 2024. The Indian stock markets overall looked very overvalued. PE ratios were above the 20 mark.
At the same time, China’s stock markets looked very undervalued. PE ratios were around the 10 mark.
This made the Chinese stocks look cheap and tempting. Economic measures announced by China further helped the cause.
So some money got moved from India to China even though the Indian companies and the economy in general were doing fine.
The opposite, buying Indian and selling Chinese stocks, had happened a few years ago for a similar reason.
Country & Regulation Level Factors
A lot of times, money moves because of factors related to a country.
When a policy shift or regulation dramatically affects its future, foreign money reacts accordingly.
This could be positive or negative.
Many times, reforms in foreign investment, debt, taxation, business environment, etc lead to money flowing into a country’s stock markets.
If things destabilize or get worse, money flows out.
In 2009-2010, the government of Greece revised its deficit numbers. It turned out that the country’s deficit was double the earlier estimate.
Investors saw this as a massive red flag and sold Greek assets en masse.
In 2023, an economically suffering Argentina elected a new president who promised massive economic reforms.
This led to investors buying Argentinian assets as the country looked more stable and reliable than before.
The Hong Kong stock exchange’s chairman shutting down the markets for 4 days was a regulation blunder. Foreign investors felt trapped. That spooked them.
The second fall — 33% fall after the markets opened was a regulation factor. Investors were afraid of future closures that would prevent them from selling if they wanted to.
Mechanical Factors
This one’s a bit non-intuitive but very real.
We are aware that index investing has become a prominent style of investing in the West.
Index funds usually follow an index. And constituents are added/removed from various indices based on fixed formulas.
We in India are used to Nifty 50 index funds. These invest only in Indian stocks.
But globally, there are index funds that invest in companies across the globe.
When a stock gets added or removed from these indices, money can flow into or away from that stock.
Though not always, many times this flow of money can be significant.
When the Russia-Ukraine conflict started in 2022, sanctions meant that economic ties with Russia were cut.
This also meant that Russian bonds and stocks were no longer allowed to be part of global indices.
Since the nature of the indices were changed, the index funds had to rebalance that money according to the new constituents.
More recently, Indian bonds were added in an index by JP Morgan. At that point, some forecasts estimated an inflow of about $25 billion into Indian bonds because of this.
One peculiar case was back in the late 1980s, in Japan.
Index funds were made based on a formula, and as long as that formula included Japanese stocks, they remained invested in Japanese stocks.
Many active fund managers were of the opinion that the Japanese markets were extremely overvalued.
But they worried about missing out on potential returns (compared to index funds). So many fund managers chose to stay invested in Japan.
This example clearly shows that not all money moves when a certain market seems overvalued.
Sometimes, money just stays put despite being overvalued. And hence, money doesn’t move when it logically should.
Why Money Moves
The point of all of this is to try and explain why money moves in the global financial system.
While it is easy to point out a reason, or assume something else, one must remember that at any time, there are multiple factors at play.
The above stated reasons are all individually acting.
But they are also acting along with each other.
So, not all rate hikes will result in more money moving to less-risky investments.
Sometimes, the opposite of what you’d expect may happen.
Each major money movement must be analyzed. But looking at them only individually is not enough. They all work together.
It also explains why in many cases, the markets move against our expectations.
The economy of a country might be doing well, but money starts moving out of its markets simply because some other country’s stocks look more attractive in that year.
Rates may be hiked, but because of some bullish sentiment, money may continue moving towards high-risk investments.
Quick Takes
+India’s retail inflation rose to 5.54% in September from 4.83% in August. Rural inflation at 6.08% (vs 5.24%) and urban inflation at 4.88% (vs 4.31%).
+Equity mutual fund inflows rose 30.61% to Rs 38,306.55 crore in September. The outflows from debt funds widened to Rs 1.83 lakh crore in September compared to Rs 8,127 crore in August. SIP contributions reached a record high of Rs 32,490 crore in September.
+SEBI introduced a common advertisement code for regulated entities (stock brokers, research analysts, mutual funds, etc). Celebrities can now promote these entities, brands but cannot endorse specific products or services, without approval.
+US President Trump lifted sanctions on Russian fuel and said that Russia agreed to supply diesel to global markets till April 2027, to lower rallying fuel prices.
+RBI announced to sell dollars to meet the entire daily dollar requirements of oil marketing companies (OMCs) among other measures to support the rupee.
+MDR on UPI transactions has been postponed until after Diwali, keeping the festive season in mind. The new start date has not been announced yet.
+The IMF raised India’s economic growth forecast to 7% for FY27 (earlier forecast was 6.4%). Forecast for FY28 was also increased to 7% (vs 6.7% earlier).
+The government approved the sale of 60.72% stake in IDBI Bank to Canada-based Fairfax Financial Holdings for Rs 52,878.08 crore as part of the bank’s strategic restructuring.
+India’s wholesale inflation rose to 11.39% in September compared to 9.92% in August driven largely by fuel and power inflation.
+India changed the double taxation avoidance agreement (DTAA) with Mauritius to prevent investors from using Mauritius-based entities primarily to get tax benefits.
+SEBI extended the timeline for companies to adjust their IPO sizes by up to 50% without the need for new approvals. This is applicable to IPOs that open on or before 31 March 2027, as per media reports.
+Jio Platforms filed its RHP with SEBI for an IPO to raise around Rs 28,755- 30,000 crore, making it the biggest IPO in India. The IPO comprises a fresh issue of 27 crore shares with no offer for sale.
+India’s exports rose 13.84% year-on-year to $476.20 billion between April and September, compared to $418.31 billion in the same period last year.
+The government signed contracts worth Rs 4,106 crore with NewSpace India Limited and Bharat Dynamics for a dedicated communication satellite capability and heavy weight torpedoes.
+India’s unemployment rate remained at 5% in September; the same level as August. Urban unemployment rose to 6.9% (vs 6.8%) and rural unemployment rose to 4.2% (vs 4.1%).
+Passenger vehicle sales grew 30.7% to 1.36 million units in the July-Sept quarter. Two wheeler sales: up 15.2% to 6.43 million units, commercial vehicle sales: up 28.7% to 3.09 lakh units: SIAM.
+India’s net direct tax collections rose 13.21% year-on-year to Rs 13.38 lakh crore as of 14 Oct.
+SEBI revised the CAS framework to calculate the reference price for closing auctions based on volume-weighted average price (VWAP) of trades. The changes will take effect from 7 Dec.
+India’s forex reserves fell $8.58 billion to $726.03 billion for the week ended 9 Oct.
+The government raised windfall tax on petrol exports to Rs 2.5 per litre (vs Rs 0.5 earlier). The duty on diesel exports was cut to Rs 8.5 per litre (vs Rs 16 per litre).
+India’s current account deficit narrowed to $5.2 billion in August compared to $6.1 billion in August a year ago.
+Mutual funds stopped accepting new investments in gold fund of funds (FoFs) from 16 Oct due to verbal restrictions imposed by SEBI, as per media reports.
+Indian Gas Exchange Ltd, Cult.fit Ltd and 2 others received SEBI approval for IPO.
The information contained in this Groww Digest is purely for knowledge. This Groww Digest does not contain any recommendations or advice.
Team Groww Digest